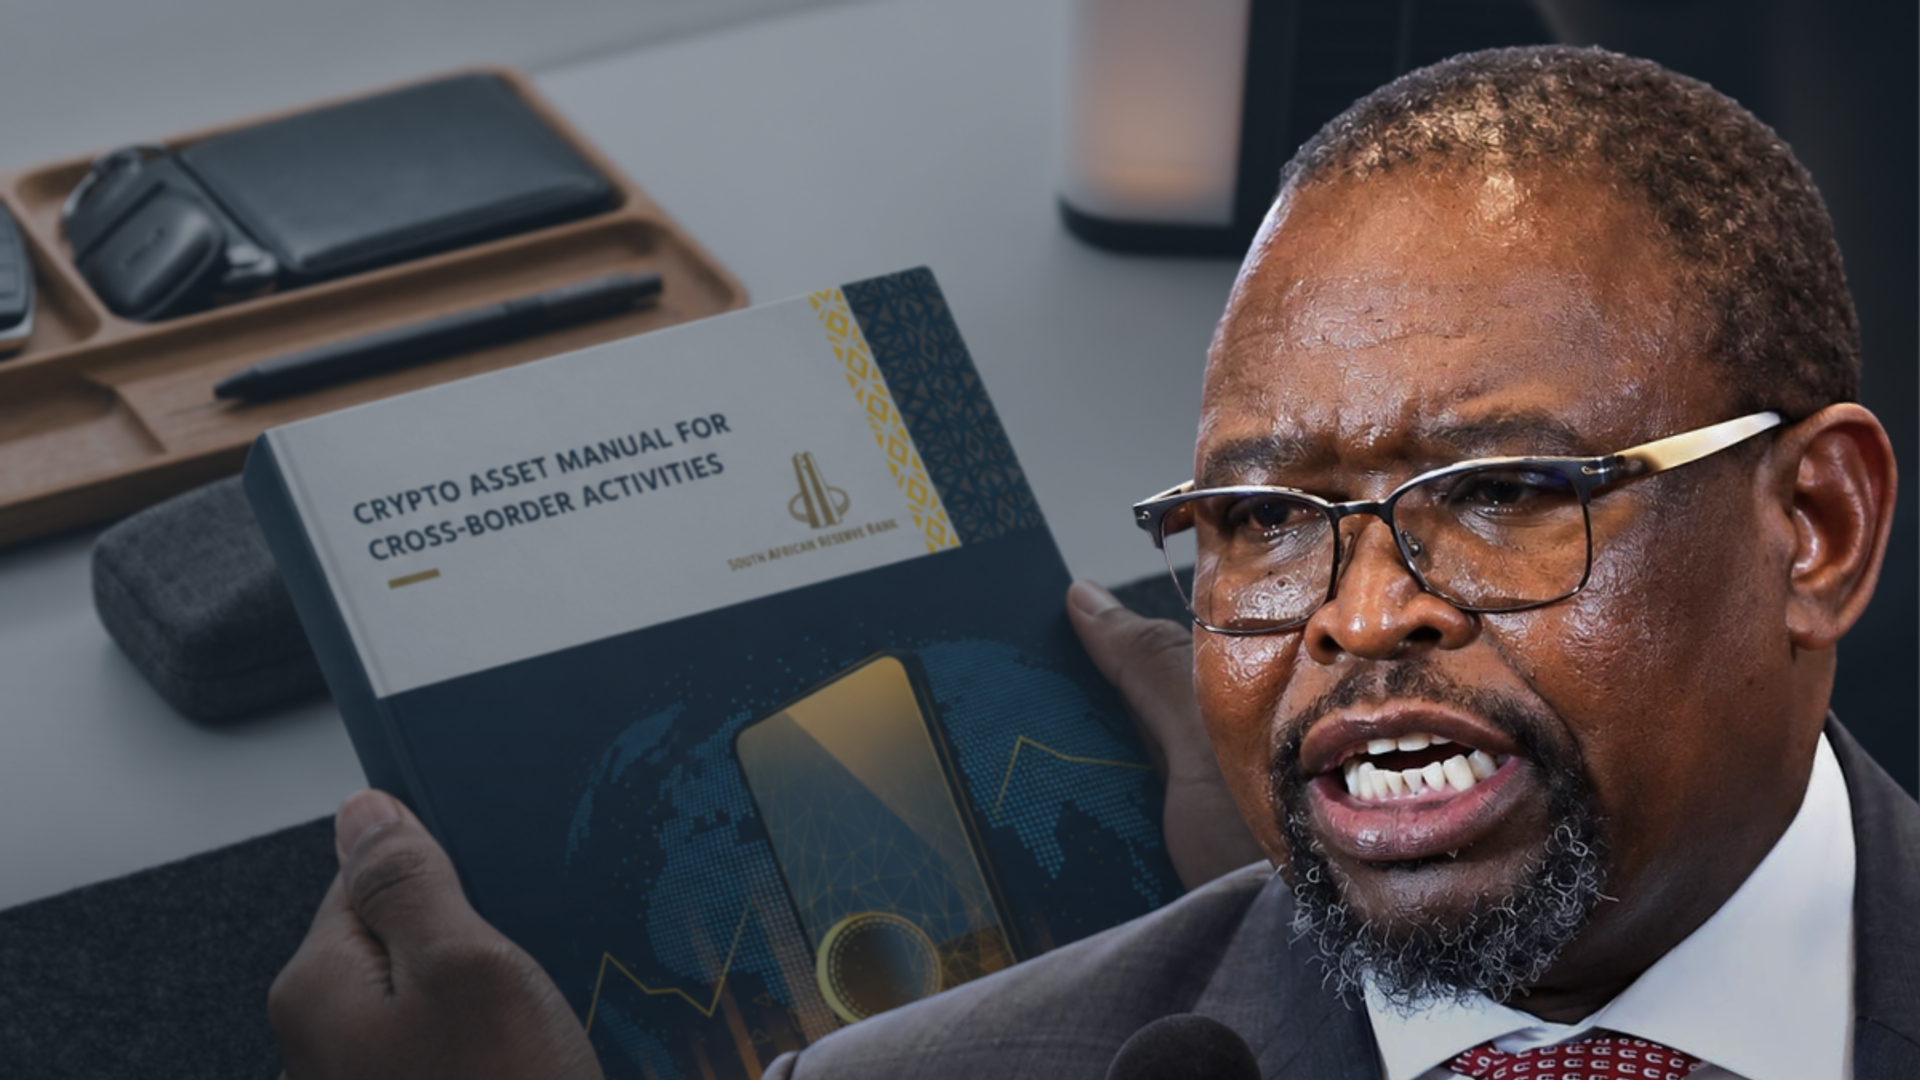
Sakeliga opposes draft rules for cross-border crypto transactions
The Draft Manual would restrict lawful economic activity by businesses and individuals, and would give officials unconstrained power over private property.


Sakeliga notes the announcement by Finance Minister Enoch Godongwana, in the Medium-Term Budget Policy Statement of 21 October 2026, that National Treasury and the South African Reserve Bank (SARB) will consult on a redrafting of the Draft Capital Flow Management Regulations, which include proposed cross-border crypto rules.
Sakeliga is of the view that the subsequent Draft Crypto Asset Manual for Cross-Border Activities (published in August 2026) should also be retracted, as it is based on the Draft Capital Flow Management Regulations.
Our written comments on the Draft Regulations were submitted on 30 June 2026, and the article below sets out our objections to the Draft Crypto Asset Manual, which would operationalise the coercive powers contemplated in these regulations.
Sakeliga has submitted written comments to National Treasury and the South African Reserve Bank (SARB) opposing the Draft Crypto Asset Manual for Cross-Border Activities.
The Manual applies to any individual in South Africa who engages in, or wishes to engage in, cross-border crypto transactions, as well as any business that aims to utilise them for such transactions. It sets out who may transfer crypto in and out of the country, through which service providers, within which limits, and what the state may do when it suspects a breach.
Sakeliga rejects the Manual in its entirety on both substantive and procedural grounds. It would restrict lawful economic activity by businesses and individuals, give officials unconstrained power over private property, and lack a valid legal basis within South Africa’s statutory regulatory framework.
Restrictions on crypto asset transfers
Under the Manual, South African companies and trusts would be barred from almost all cross-border transfers of crypto assets, a restriction that ironically encompasses inward capital flows from foreign sources into the domestic market and economy. No adequate justification is provided for this prohibition.
Individuals will face similarly far-reaching and absurd restrictions. The Manual restricts a person who holds crypto assets in a personal wallet from transferring them to a South African exchange, even though the assets are being brought into the regulated domestic system.
The Manual also leaves it to SARB’s Financial Surveillance Department (FinSurv) to determine what constitutes a cross-border transaction. Read together with the Draft Regulations’ expansive definition of “capital” as “anything with a monetary value”, this effectively allows FinSurv to determine the scope of its own regulatory jurisdiction, potentially extending its reach to purely domestic transactions.
Disclosure of private keys
Possession of a private key generally gives its holder effective control over the crypto assets associated with it.
In terms of the Manual, Crypto asset service providers applying for authorisation would have to disclose how they store and safeguard their clients’ private keys. Separately, the Draft Regulations intend to empower officials to call for “any information in any manner” without prior judicial authorisation. Taken together, these provisions would effectively empower officials to compel the disclosure of private keys, giving them the means to gain control of and potentially seize an individual’s crypto assets without a court order.
At the same time, directors, shareholders, and beneficial owners of applicant service providers would be required to unconditionally indemnify FinSurv against liability arising from data breaches related to the processing of their personal information, including the accidental disclosure of sensitive information to unauthorised persons.
Warrantless searches and seizures
The Manual directs service providers to exercise extensive powers to demand information and conduct searches of premises.
FinSurv itself could seize documents and records based on its own suspicion of non-compliance, without a court order or prior notice.
Furthermore, official authorisation for a service provider could be suspended or permanently withdrawn by the SARB without a prior hearing or an express right of appeal. Under Section 5 of the Promotion of Administrative Justice Act 3 of 2000 (PAJA), public entities such as National Treasury are granted up to 90 days to provide written reasons for such administrative decisions, following a request for reasons from an affected person or business. During this interim period, an affected party, such as a suspended service provider, could incur significant and irreversible commercial losses.
A procedurally flawed consultation process
Treasury and the SARB state that the Manual has not yet taken into account the comments already submitted on the Draft Regulations, including Sakeliga's comments.
Requesting public input on an operational instrument while its underlying framework remains under active consideration fundamentally undermines the integrity of the public participation process.
Sakeliga also objected to the prescribed clause-by-clause table format for submissions. The format assumes the framework's validity, limits submissions to minor reforms, and structurally excludes the fundamental position that the Manual ought to be rejected in its entirety.
Resources

Help us secure a flourishing economy
You can restore economic order by funding our work.